All Categories
Featured
Sub-Saharan African nations represent around one-third of the overall, followed by Latin America and the Middle East (the latter 2 together representing over 40% of the total). Including, there has actually been an (from 90.3 in 2000-04 to 92.6 and 92.3 in the five years pre- and post-pandemic ).
and ranked higher than others; UAE is up more than 45 places in 2024 compared to 2000 while Qatar climbed up 24; both Saudi Arabia and Oman increased 17 ranks throughout the period. The caught or worse off nations are some parts of Latin America and Sub-Saharan Africa where structural improvement has stalled.
reveals a considerable boost in typical EDI ratings from 86.8 in 2000-04 to 92.6 in 2020-24, (up more than 10 points in the preliminary duration versus 2020-24). with UAE outperforming in the trade sub-index (supported by recent bilateral trade agreements & non-oil exports push). vs its pre-pandemic reading (partly given the surge in medium & state-of-the-art production information).
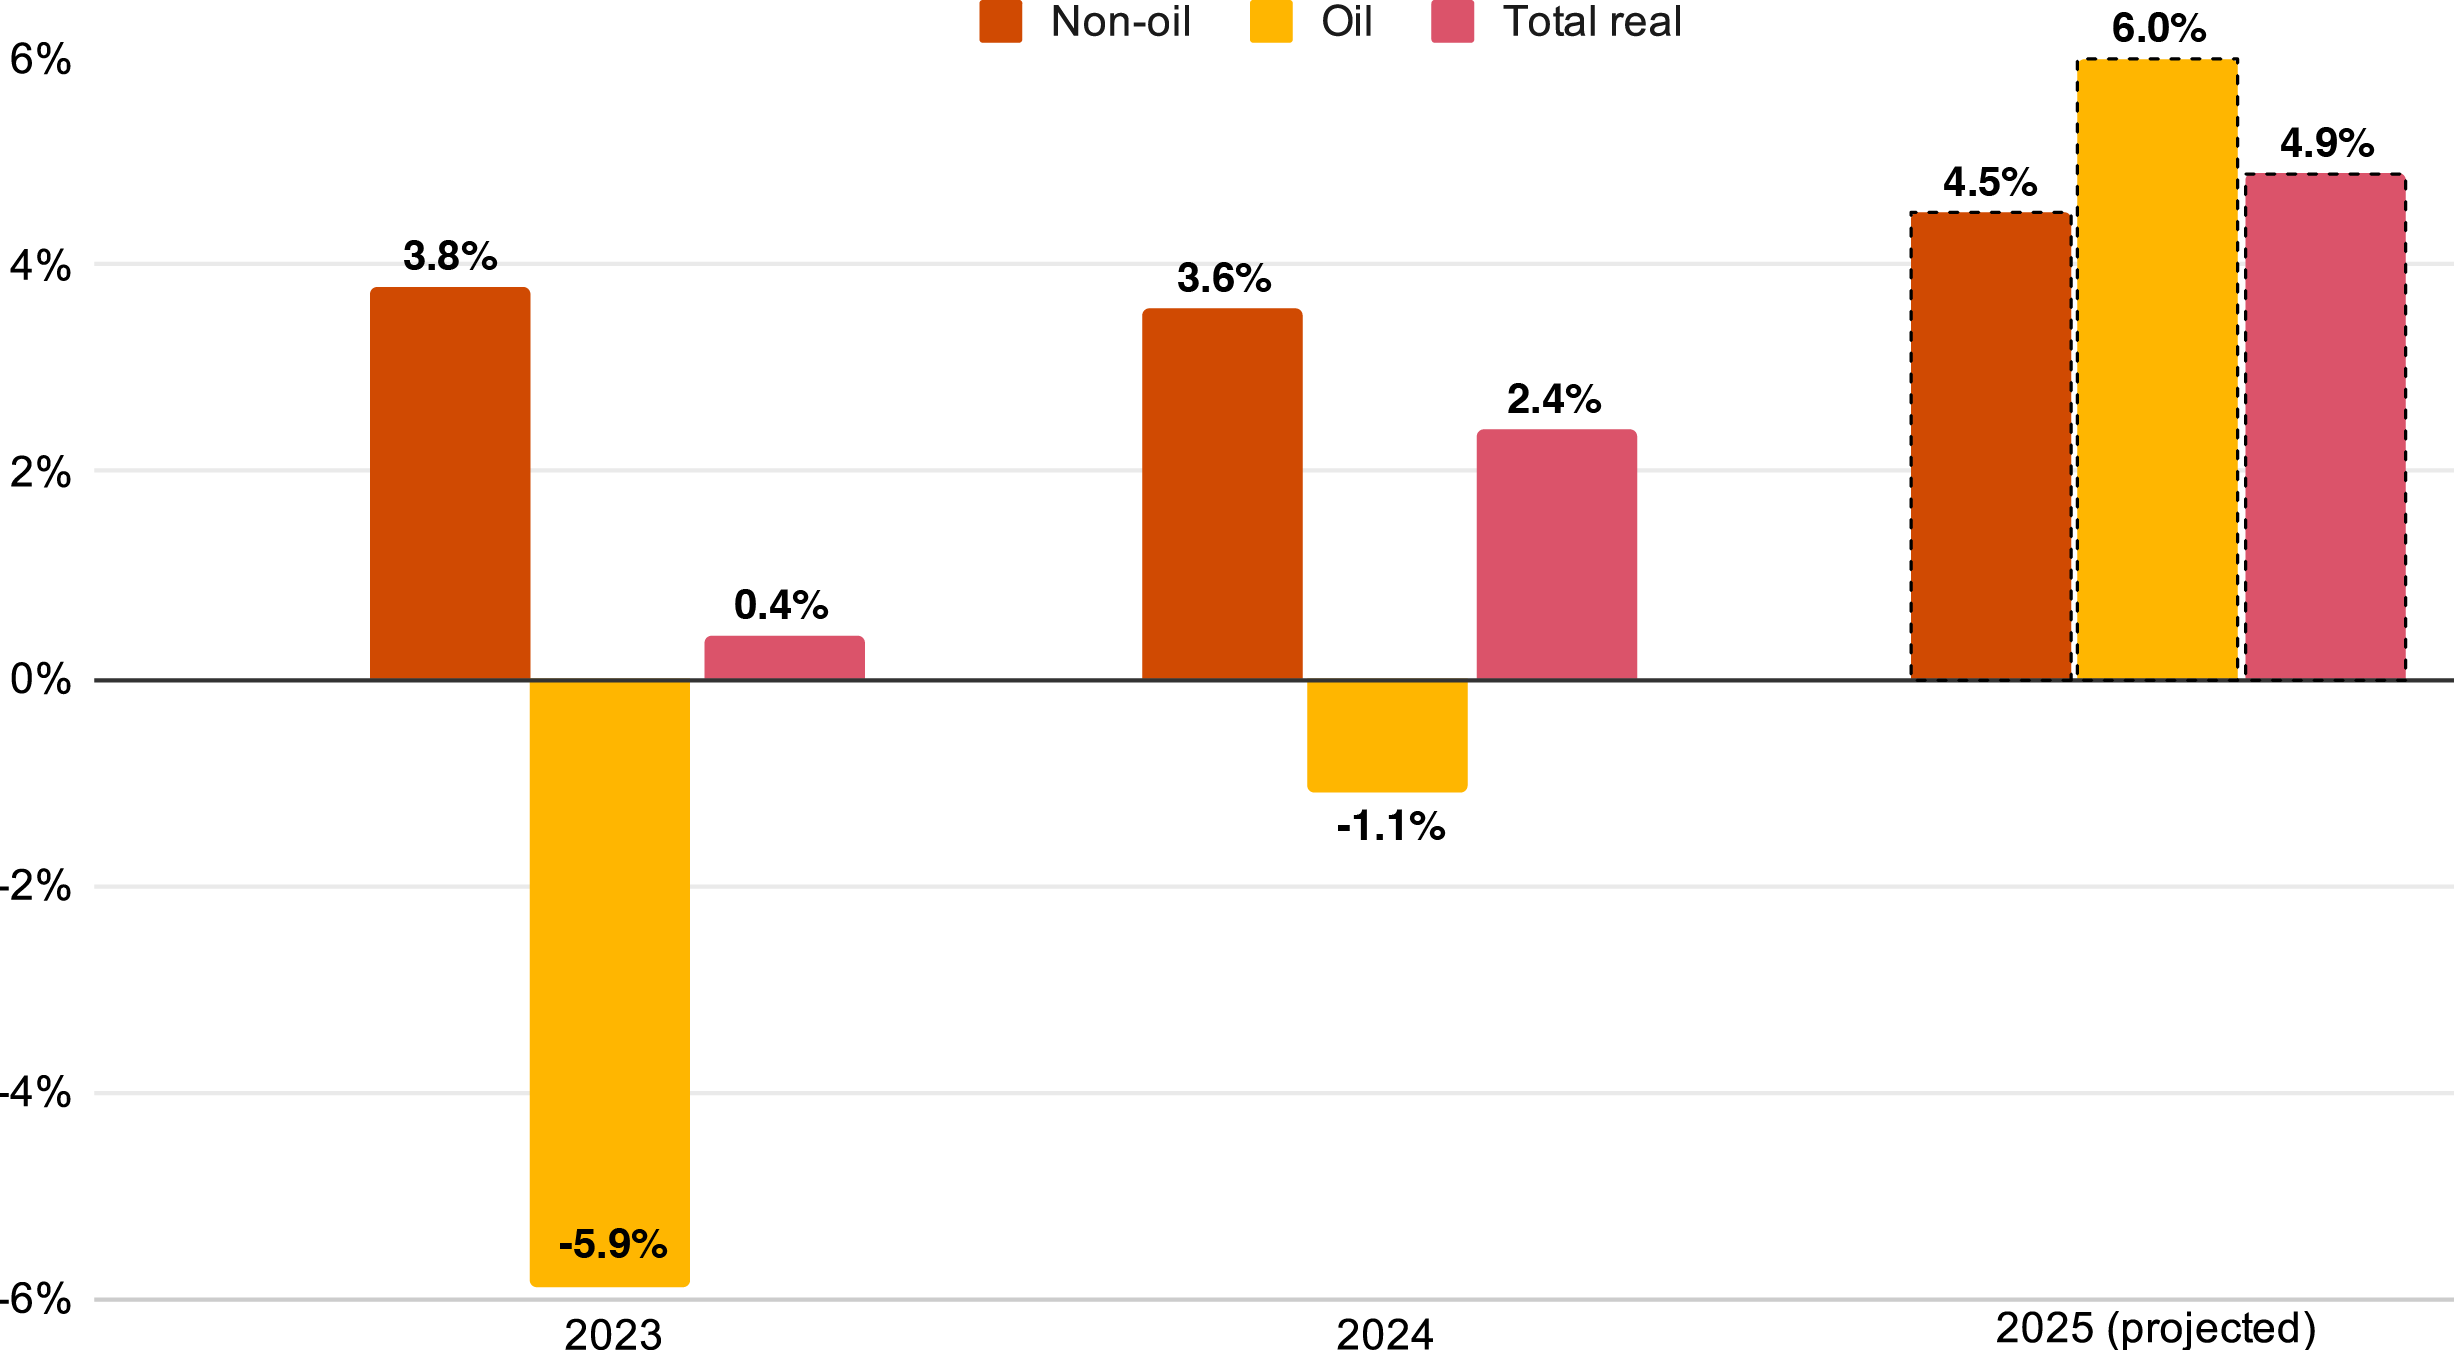
Its diversification metrics have stagnated, showing the least enhancement between the initial (2000-04) and final (2020-24) reference periods., in spite of the headwinds of OPEC+ production cuts. A robust non-hydrocarbon expansion was supported by the GCC's robust domestic need (supported by a strong job pipeline and execution) and strong services sector efficiency.
Why ESG Ratings Matter More Than Ever for Gulf BusinessesFrameworks for Capital Allocation in 2026 Global Markets
Kuwait and Saudi Arabia clocked in a boost in non-hydrocarbon earnings, "mainly showing non-hydrocarbon tax base expansions and profits collection performance improvements", according to the IMF. In the existing geopolitical environment defined by heightening, it remains in the best interests of product reliant nations to diversify its export base, exports and trade partners.

Latest Posts
Comparing GCC Investment Climates vs Global Markets
Positioning Middle East Portfolios against 2026 Trends
The Rise of Regional Industrial Hubs